1 store
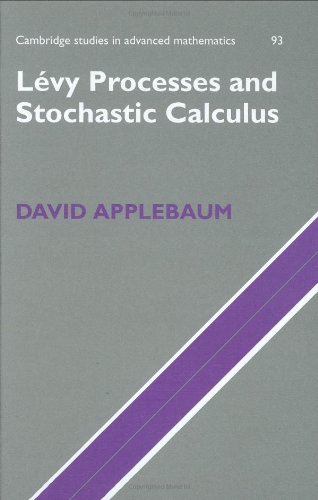
Lévy Processes and Stochastic Calculus (Cambridge Studies in Advanced Mathematics, Series Number 93)
Compared at 1 store·Used
·Updated 11 days ago
Lowest $53.21Highest $53.21
Compare buying options
One live offer. The cheapest is used.Sold byDetailsSpecial savingsItem price
Product Description
Lévy processes form a wide and rich class of random process, and have many applications ranging from physics to finance. Stochastic calculus is the mathematics of systems interacting with random noise. David Applebaum connects the two subjects together in this monograph. After an introduction to the general theory of Lévy processes, he accessibly develops the stochastic calculus for Lévy processes. All the tools needed for the stochastic approach to option pricing, including Itô's formula, Girsanov's theorem and the martingale representation theorem, are described.
Set Price Drop
Get an alert as soon as it’s on sale.
Alert set
Your price
Lowest now$53.21
We’ll let you know when any store drops to your price or lower.
Video reviews
Reviews of this product on YouTube.Just For You
Stores we recommend, with today’s cash back rates. Activate & Shop
eBay
Up to 1.5% Cash Back
10% Off Select Items
 Activate & Shop
Walmart
Up to 12% Cash Back
Up to 65% Off Select Items
 Activate & Shop
Temu
Up to 40% Cash Back
Up to 30% Off Select Items
 Activate & Shop
AbeBooks
2.5% Cash Back
Free Shipping For Select Items
 Activate & Shop
Alo Yoga
4% Cash Back
Up to 40% Off Select Items
 Activate & Shop
The Home Depot
Up to 8% Cash Back
Up to 40% Off Select Items
 Activate & Shop
eCampus.com
Up to 4% Cash Back
 Activate & Shop
Alibris
2% Cash Back
 Activate & Shop
Etsy
3.7% Cash Back
Up to 75% Off Select Items
 Activate & Shop
Transparent Labs
5% Cash Back
 Activate & Shop
Chewy
1% Cash Back
50% Off First Autoship
 Activate & Shop
BiggerBooks
3.5% Cash Back
7% Off